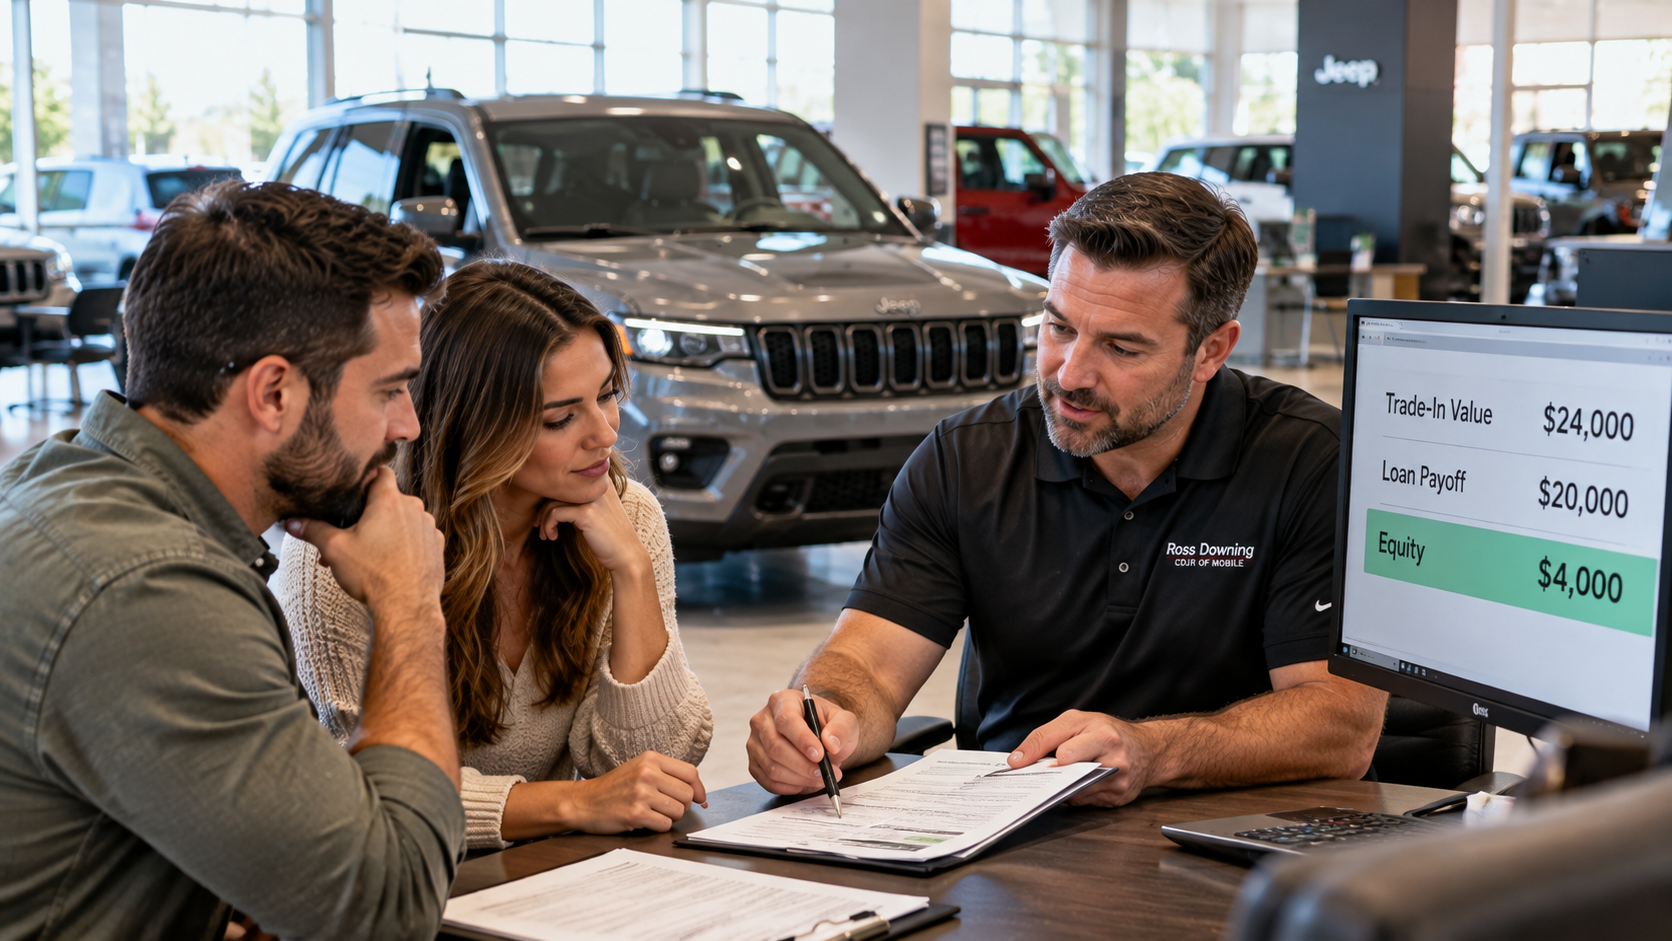
Used car dealer Mobile AL visits can include a trade that still has an active loan. The old loan does not disappear when the trade begins. Therefore, the dealership must compare your trade value with the lender payoff before the next financing step. That comparison shows whether you have positive equity or negative equity. It also shows how much old debt, if any, remains after the trade value is applied. Knowing those numbers separately can make the finance discussion easier to follow.
Start With Trade Value and Current Payoff
Can you trade a vehicle that still has a loan? Yes, but the current payoff must be reviewed alongside the trade value. The trade value reflects what the dealership offers for the vehicle. By contrast, the payoff shows what your lender requires to close the existing loan.
Those numbers can be different for several reasons. Your payoff can include interest that has accrued since the last statement. In addition, recent payments or account charges can change the final amount due. Therefore, a monthly statement balance may not equal the current payoff.
Used car dealer Mobile AL shoppers should request a current payoff before finalizing the trade. That figure should come from the existing lender. The dealership can then compare it with the appraisal.
Suppose your trade is valued at $24,000 and your payoff is $20,000. In that case, the difference is $4,000 in positive equity. If the payoff is $27,000, the difference is $3,000 in negative equity.
Before moving forward, review these numbers separately:
- Confirm the trade value before discussing how the old loan will be settled.
- Verify the current payoff with the lender instead of relying on an older statement.
- Subtract the payoff from the trade value to see the equity amount.
As a result, you can see the trade position before the next loan enters the discussion.
Calculate Positive or Negative Equity
What happens when the trade value is higher or lower than the payoff? The difference becomes either positive equity or negative equity. Positive equity means the trade is worth more than the amount still owed. By contrast, negative equity means the payoff is higher than the trade value.
Positive equity can reduce the amount you need to finance on the next vehicle. Therefore, a $4,000 positive equity amount can work much like part of a down payment. The exact transaction still includes taxes, fees, and other purchase details.
Negative equity works differently. The unpaid amount remains after the trade value is applied. Therefore, that balance still needs to be addressed before the old loan can close.
A used car dealer Mobile AL shopper should look at the equity figure before discussing monthly payment. Otherwise, the trade position can become difficult to follow once the next loan terms appear.
The equity calculation itself is simple. Trade value minus payoff equals the equity amount. A positive result shows equity available toward the next purchase. A negative result shows the remaining balance that must still be handled.
That math does not tell you whether a new loan will be approved. However, it gives you a clear starting point before lender review begins.
See How Negative Equity Changes the Next Loan
What happens if negative equity goes into the next loan? The unpaid balance can increase the amount financed on the next vehicle. Therefore, the new loan may include both the next purchase and part of the old debt.
Suppose the next vehicle costs $30,000 before taxes and fees. Now assume the trade creates $3,000 in negative equity. If that $3,000 is included in the next loan, the financed amount rises before other costs are added.
Therefore, the new loan can start at a higher balance than the vehicle price alone suggests. That can also raise the loan to value ratio. Lenders may review that ratio when deciding how much they are willing to finance.
Used car dealer Mobile AL shoppers should ask where the negative equity appears in the paperwork. It should not be hidden inside a monthly payment discussion. In addition, review the amount financed, rate, and term as separate figures.
Negative equity can also change total interest costs. A larger financed amount can create more interest across the loan term. Therefore, a lower monthly payment does not always mean a lower total cost.
Before signing, compare the loan structure in this order:
- Review the next vehicle price before trade credit enters the calculation.
- Review the negative equity amount that remains after the trade.
- Review the final amount financed after taxes, fees, and other charges.
That order makes it easier to see where each dollar enters the contract.
Keep the Trade and Financing Numbers Separate
Which numbers should you review separately? Start with trade value, payoff, equity, vehicle price, amount financed, rate, term, and monthly payment. Therefore, each figure answers a different question in the transaction.
The trade value shows what the dealership offers for your current vehicle. By contrast, the payoff shows what the lender requires to close the old loan. Equity shows the difference between those two numbers.
The next vehicle price is a separate figure. Therefore, it should remain visible before financing details are added. The amount financed then shows how much money the new loan will cover.
Rate and term shape the repayment plan. In addition, the monthly payment comes from those inputs. A longer term can reduce the payment while keeping the financed amount high.
Used car dealer Mobile AL shoppers should avoid judging the deal through payment alone. A payment can move because the term changes. It can also move because the rate, down payment, equity, or financed amount changes.
Ask to see the trade and loan figures one by one. Therefore, you can trace any change back to its source. That makes the final contract easier to review before signing.
Prepare Before Trading a Financed Vehicle in Mobile
What should you bring before trading a financed vehicle? Bring the information needed to verify ownership, lender details, payoff, mileage, and identity. Therefore, that preparation can shorten the time spent collecting basic information at the dealership.
Start with your registration and lender information. In addition, bring any recent payoff quote you already have. The dealership may still request a fresh payoff before closing the old loan.
Also bring both keys, current mileage, and service records that relate to recent work. These items can support the appraisal and reduce missing details during the visit.
Used car dealer Mobile AL shoppers can also review financing steps before arriving. Ross Downing CDJR of Mobile offers online finance resources for early preparation. Therefore, you can organize the trade and financing information before the dealership visit.
Keep these items together before you leave home:
- Registration, lender details, payoff information, and photo identification.
- Both keys, current mileage, and records for recent service or major repairs.
- Any down payment information or financing documents requested before the appointment.
After the transaction closes, verify that the old lender received the payoff. That final check confirms that the prior loan has been satisfied. Therefore, the trade process should end with a clear record of both the old loan and the new financing.