Bad credit dealerships can use different financing structures, so knowing what happens before a credit application matters. A clear financing conversation should explain when credit will be reviewed and who may review it. Moreover, you should know which loan figures deserve attention before signing. APR, loan term, amount financed, finance charge, and total payments all tell a different part of the story. In addition, dealer arranged lending differs from in house financing. Understanding those steps gives you a clearer way to review each offer before accepting it.
What Happens When You Authorize a Credit Check?
A credit application gives a lender or dealership permission to request credit information for a financing decision. What happens after you sign or submit that application? The next step may involve a hard credit inquiry from a prospective lender.
A hard inquiry appears when a lender reviews your credit after an application. Therefore, it can appear on your credit report and may change your score. By contrast, a soft inquiry does not lower your score. Soft inquiries can appear during certain account reviews or prequalification steps.
The phrase credit check can sound simple, but the type of inquiry matters. For this reason, ask whether the next step uses a hard or soft inquiry. You should also ask when that inquiry will happen.
Bad credit dealerships may work with outside lenders that review applications individually. In that structure, authorization may lead to several lender reviews. Therefore, knowing the lender process before submission keeps the conversation clear.
The dealership should also explain what information the application covers. Income, housing details, employment information, requested loan amount, and credit history may all enter the review. In addition, lenders may use different approval standards.
Before submitting anything, ask who receives the application and what type of credit review may follow.
Why Might Several Auto Loan Inquiries Appear?
Dealer arranged financing may send one application to several lenders seeking available loan terms. Why would that happen? Different lenders may offer different APRs, terms, or approval structures for the same applicant.
A dealership may send the application to several lending partners. Therefore, multiple lender names can appear on a credit report after one finance application. That does not always mean you completed several unrelated applications.
Auto loan shopping also receives special treatment under common credit scoring models. Multiple auto loan inquiries made within a short period may be grouped for scoring. The exact window can vary by scoring model. Therefore, the timing of your applications matters.
For this reason, complete serious rate shopping within a focused period when possible. That can include dealership financing, banks, and credit unions. In addition, an outside preapproval can give you another offer to compare.
Bad credit dealerships that use outside lenders may receive several responses from one application. Some lenders may decline the request. Others may return different rates or loan terms. Therefore, ask how many lenders may receive your information before the application moves forward.
A transparent conversation should explain the lender outreach before you see several inquiries later.
What a Clear Loan Offer Should Show
A clear auto loan offer should show more than the monthly payment. Which figures deserve your attention first? Start with APR, loan term, amount financed, finance charge, and total payments.
APR shows the annual cost of borrowing. Therefore, two loans with the same vehicle price can carry different borrowing costs. A lower monthly payment does not automatically signal the lower cost.
Loan term shows how long you will make scheduled payments. A longer term can reduce each payment because repayment spreads across more months. However, the total cost of borrowing can rise.
Amount financed shows the principal carried into the loan. That figure may reflect the vehicle price after down payment, trade credit, and selected products. In addition, optional products can raise the amount financed.
Finance charge shows the stated dollar cost of credit under the agreement. Total payments shows how much all scheduled payments add together. Therefore, these figures give you a clearer view beyond the monthly number.
Before choosing an offer, review these items together:
- APR should be clear before you accept the loan.
- Loan term should match the number of months you discussed.
- Amount financed should reflect the agreed transaction figures.
- Finance charge should show the stated borrowing cost.
- Total payments should show the full scheduled repayment amount.
A monthly payment makes more sense after those figures are clear.
Bad Credit No Credit Check and In House Financing
Bad credit financing, no credit check language, and in house financing do not always describe the same lending structure. A shopper may ask whether every bad credit dealership works the same way. The answer is no.
Dealer arranged financing uses outside lenders to review the application. The dealership sends the application and receives possible offers. Therefore, the final loan may come from a bank, credit union, or finance company.
In house financing uses a different structure. The dealership itself may provide or service the loan. Buy here pay here dealerships commonly use this model. Therefore, the lending relationship stays much closer to the selling dealership.
No credit check language also deserves careful review. Ask what the phrase means before assuming no credit information will be considered. Some lenders may rely on different approval criteria or alternative information.
Ross Downing CDJR Mobile states that its finance team works with local and national lenders. Therefore, its process fits dealer arranged financing instead of a buy here pay here structure.
If credit history creates concern, ask which lending route is being discussed. Then compare APR, term, down payment requirements, and amount financed before moving forward.
Questions to Ask Before You Sign
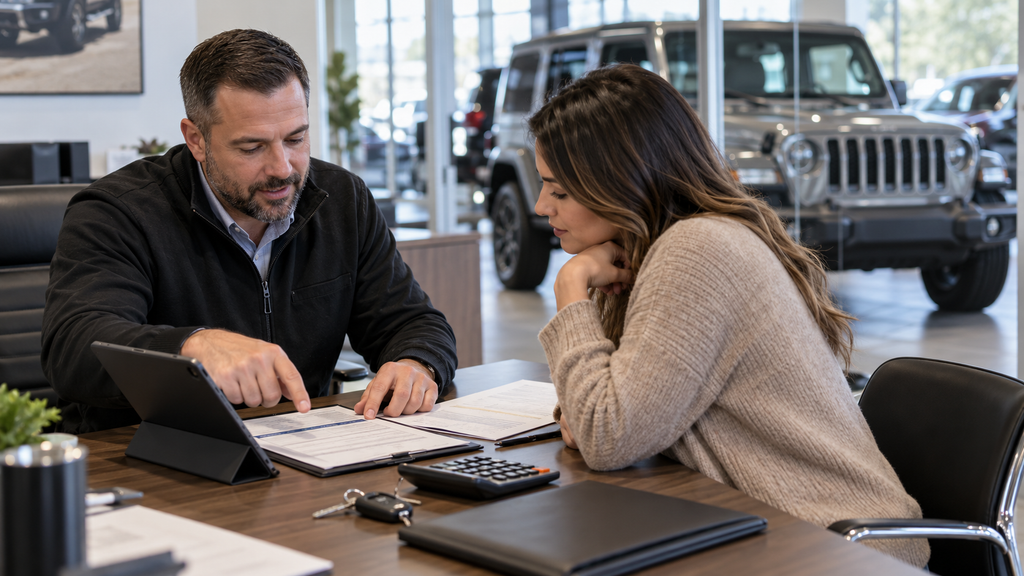
A transparent financing conversation should leave you knowing who reviewed the application and what the loan costs. Therefore, ask questions before the contract reaches the signature line.
Start with the credit application. Ask whether the next review creates a hard inquiry. In addition, ask whether the application may go to several lenders. That gives you context before lender names appear on your credit report.
Next, review the loan structure. Ask for the APR, term, amount financed, finance charge, and total payments. If an outside preapproval exists, compare it with the dealership offer.
You should also ask whether the interest rate can change between approval and contract signing. In addition, review every optional product before it enters the loan balance. No product should surprise you in the final figures.
Bad credit dealerships may present several financing routes because lender requirements differ. That makes clear communication more important before you choose. Know what type of credit inquiry may happen, who may receive the application, and which offer you are reviewing.
Before signing, make sure the loan figures match the conversation you already had. A respectful finance process gives you enough information to compare the offer before making the commitment.